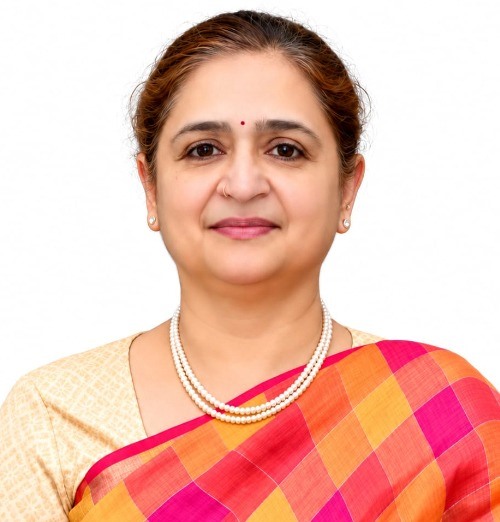
“Q2FY27 has been one of the most challenging quarters for the company in recent times, more so while succeeding another equally challenging one for the entire industry,” said Dr Lavanya R. Mundayur, CMD, New India Assurance.
Mumbai: Dr Lavanya R. Mundayur, CMD, New India Assurance, said with property premiums showing signs of stability in the industry, the company is working to strengthen its underwriting and operational efficiency.
“The company is focused on improving its operational efficiencies with improved underwriting, technological interventions in claims management across health and motor lines, besides providing innovative solutions. These measures are aimed at achieving sustainable and profitable growth,” said Dr Mundayur,who joined the insurer almost a month back.
NIA, the country’s largest general insurance multinational, had a difficult second quarter of FY2026-27, with falling property insurance rates, large-risk claims and an additional provision of Rs 715 crore in the motor third-party (TP) segment putting pressure on its underwriting performance.
“Q2FY27 has been one of the most challenging quarters for the company in recent times, more so while succeeding another equally challenging one for the entire industry,” said Dr Mundayur.
The company’s gross written premium (GWP) grew by only 5.14% during the quarter, primarily due to a steep decline in property insurance rates, stated Dr Mundayur.
“The property segment suffered significant underwriting losses as well, due to multiple large-risk losses, and flood claims in Gujarat, North India, and North East India,” Dr Mundayur highlighted.
The aviation segment also experienced adverse claims during the quarter, while motor and health insurance businesses faced challenges.
Adding to the pressure, the company made an additional provision of Rs 715 crore in its motor TP portfolio following the Supreme Court verdict recognising the economic value of unpaid domestic work performed by homemakers while determining compensation under the Motor Vehicles Act.
“Given the honourable Supreme Court verdict.based on an initial assessment of the possible losses, the company has made an additional provision of Rs 715 crore in the Motor TP segment,” Dr Mundayur said.
NIA reported a net loss of Rs 1,260 crore in the second quarter ended September 2026, against a net profit of Rs 201 crore in the corresponding quarter last fiscal.
The insurer’s gross premium income, however, increased 5.19% to Rs 11,196 crore in Q2FY27 from Rs 10,644 crore in the year-ago quarter.
She added that the lack of premium revision in the motor TP segment continued to hurt both the company and the general insurance industry.
On the investment front, NIA partly monetised its investment in NSE India during the quarter, realising around Rs 1,800 crore in capital gains.
Despite the challenging operating environment, the company’s solvency ratio stood at 1.61 times, above the regulatory control-level requirement of 1.5 times.
“
Mam..,
We are pretty sure that, things will definitely improve in all parameters, with your innovative ideas and positive vibes you spread across among all the stakeholders including external and internal customers.
Still more to focus on claims means fast
Your motor premium Discount are lower compared to.market. motor claim management is pretty slow, survey in particular.
Ma’am, I am sorry to say this, but the Branch Manager in Amritsar does not seem interested in the growth and development of the agent community. Instead, he appears to be more focused on his personal growth rather than supporting agents and helping them succeed.
Dear Mam,
Thanks for expressing the thoughts/ words on Q2 results of NIA . Your leadership will definitely drive it strongly and positive. This will not only improve the results in regards to claims, underwriting but also overall performance of NIA .
One thing very significantly to be seen that a person who is doing placement/ underwriting must also see claims and vice versa. This enables the responsibilities to the official that he or she is equally responsible for placement / underwriting and claims also if any triggers. This will definitely results ICR to come down and claims pendency’s less.
Agents are not in a comfort zone and insured is not allowed to change his agent as well office and now a days in charge is not a competent and not punctual in office work. insured is never getting excellent customer seevice like cashless and quick settlement of claims. Withdraw circular like NOC for renewal with other office so that existing agent give more services