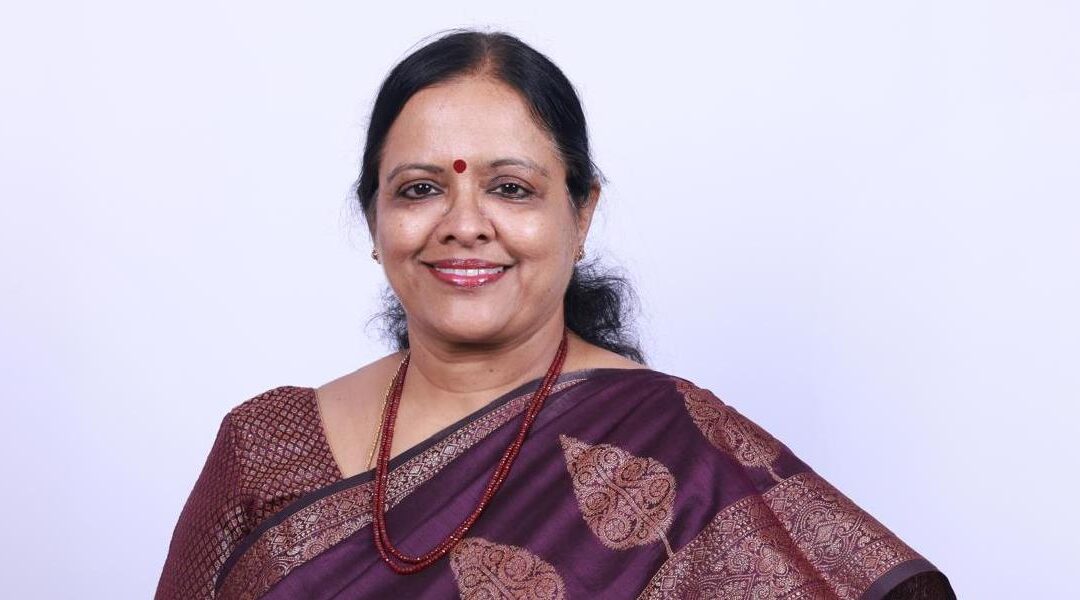
Girija Subramanian,member, Distribution, IRDAI
The effective dates under consideration are Jan. 1 and April 1, said Girija Subramanian,member, Distribution, the Insurance Regulatory and Development Authority of India(IRDAI).
India’s insurance regulator may implement sweeping distribution reforms as early as January, pushing ahead with an overhaul that has battered shares of insurers and brokers.
The effective dates under consideration are Jan. 1 and April 1, said Girija Subramanian,member, Distribution, the Insurance Regulatory and Development Authority of India(IRDAI).
The potential January start underscores the regulator’s determination to reshape the economics of selling insurance in India after concluding that an earlier liberaliSation failed to improve cost discipline.
Irdai last month proposed capping commissions paid by insurance companies to brokers and other distributors in a bid to lower fees for consumers and encourage more people to take out insurance. The caps would apply to most forms of insurance, including health, life, property and casualty. The regulator also plans to enforce lower management expenses over time to help bring down costs.
The Insurance Brokers Association of India has warned that the changes could affect as many as 1 million jobs. Brokers have been in talks with the Irdai as they seek changes to the proposals.
Subramanian rejected concerns that the overhaul would lead to large-scale job losses. She said the reforms should instead generate employment by widening the distribution network and making it easier for new participants to enter the insurance business.
The regulator says commissions have grown faster than premiums since rules were relaxed in 2023, while higher distribution spending hasn’t produced a corresponding expansion in insurance coverage.
Irdai argues that commission caps require a faster approach than expense reductions.
Phasing them in could encourage distributors to accelerate sales ahead of each reduction, potentially increasing the risk of mis-selling, according to Subramanian.
“There is an earlier-the-better case, but getting the reforms right is more important than getting them early,” she said.
Insurers, brokers and other stakeholders have until Oct. 25 to submit comments on the consultation paper. Irdai will examine these suggestions before issuing draft regulations, Subramanian said. Those rules will then be opened for another round of public feedback before the final framework is issued.
The proposals triggered a sharp selloff in companies exposed to insurance distribution. PB Fintech Ltd., the parent of online insurance marketplace Policybazaar, tumbled 36% when the moves were announced. Turtlemint Fintech Solutions Ltd. has plunged by half since then.
The measures could slash fee income for banks and digital brokers by as much as 90% in high-margin categories, according to analysts. The risks are higher for fintech platforms including PB Fintech and Turtlemint as the proposed 10% cut in new business commission rates translates to a 10%-12% fall in their earnings, according to Jefferies Financial Group Inc.
Expenses at private life insurers have climbed to about 22% of total premiums, from 16% in fiscal 2021. Those at private general insurers have risen to roughly 32% from 25% in fiscal 2019, according to Irdai. Rewards paid to distributors have in some cases added 30% to 60% to base commissions.
The regulator is giving insurers time to adjust to tighter expense limits. The reductions would be phased in over five years, with the first interim milestone in the financial year ending March 2029.
The proposed commission overhaul has parallels elsewhere in Asia. China’s regulator in 2023 required commissions paid by insurers to match rates filed with the regulator, effectively imposing a cap. Average bancassurance commissions subsequently fell by about 30%, forcing banks and insurers to renegotiate distribution agreements.
Bloomberg