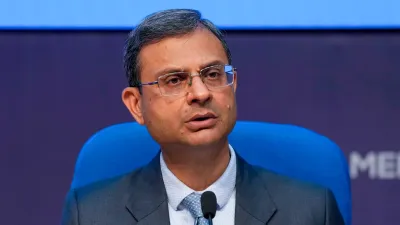
“It is primarily, I think, to consumer interest, to reduce costs and also at the same time to prevent mis-selling,” said RBI Governor Sanjay Malhotra .
Mumbai: RBI Governor Sanjay Malhotra has insurance regulator IRDAI’s proposed distribution reforms, saying the regulator’s focus on reducing costs and curbing mis-selling is in the interests of both consumers and the insurance industry.
Commenting on the sweeping changes proposed by the IRDAI to recalibrate the economics of insurance distribution, during the customary media interaction following Wednesday’s announcement of the bi-monthly monetary policy, Malhotra said the regulator had put forward draft proposals and would consider feedback from all stakeholders before finalising the framework.
“The regulator obviously has put on certain drafts, so they will take comments from all stakeholders, including the industry and consumer groups,” Malhotra said.
He said the proposed reforms were primarily aimed at protecting consumer interests while bringing down the cost of insurance distribution.
“It is primarily, I think, to consumer interest, to reduce costs and also at the same time to prevent mis-selling,” he said.
The IRDAI consultation paper on recalibrating the economics of insurance distribution has proposed a significant overhaul of the existing expense and commission framework. The regulator has suggested tighter limits on distribution costs, greater transparency in remuneration and safeguards against practices that could encourage mis-selling.
If you want to cut the commission but give fixed salary to the insurance advisor so he can survive his family
Insurance sales person not getting commission for only selling policy he or she will getting all of that who rejected for taking policy as per that the commission is must be revised on inflation base just like salary
First control salarised people who control agents.
Just turn your gaze in that direction for a moment, and you will realize who is actually driving up the costs. An agent reaches a commission level of ₹65,000–₹70,000 only after 15–20 years of hard work, whereas a salaried employee earns ₹80,000–₹90,000 right from the very first month.
Shame on the IRDAI.
Or perhaps, directly or indirectly, massive benefits are being funneled to the companies—ostensibly for the customer’s sake, but ultimately to the company’s advantage.
True said . I also believe if salaries are hiked then why commission is rescuing.. it’s totally biased decision..
A big drastic cut in commission will benefit the consumer at the same time Co’s , Banks will incur big loss affecting profitability ,putting pressure on Agents and employees. So reasonable commission is welcome.
Sir these people are getting fat salaries from govt without any commitment except pleasing their bosses.
They entirely depend on this income for their earning .these people do not know the real problem faced by a lone agent who toil on the road to secure small policy.They think that securing a policv is very easy.
The insurance advisor has to visit client umpteen time spending money from his pocket to secure a policy
Who is going to reimburse this?
Will the person deciding changes is going to pay or the insurance company NO
They enjoy tax payers money with fat salaries and the preach .that is the pity.
I have Worked for private insurance company for 25 yrs, they don’t give anything even a small health insurance cover for a senior citizen.
They have no gratitude.
Where these govt employees get life time pension and fat retirement payout. We get nothing.
That is the situation. Very bad bureaucrat without proper understanding of normal man’s life
I would like to express my serious concerns regarding the potential impact of the proposed reforms on the insurance industry, particularly on insurance penetration, customer retention, the role of intermediaries, and employment.
1. Impact on Insurance Penetration and Customer Retention
At present, customers benefit from competitive insurance premiums through the discounts offered by intermediaries. If the proposed reforms are implemented in their current form, intermediaries may be compelled to reduce or restrict the discounts offered to customers, potentially resulting in more policies being sold at standard tariff rates.
This could increase the cost of insurance for customers, discourage renewals, and make insurance less affordable for price-sensitive segments of the population. Ultimately, a reform intended to improve the insurance ecosystem could unintentionally affect insurance penetration and customer retention.
2. Importance of Fair Remuneration for Intermediaries
Insurance intermediaries play a critical role in advising customers, understanding their requirements, explaining policy coverage, comparing available options, and helping them select appropriate insurance products. Their contribution goes beyond merely selling a policy.
Fair and reasonable remuneration is essential to sustain this advisory function. If commissions are reduced significantly, intermediaries may face financial pressure that could affect their ability to provide adequate service and maintain their advisory teams. There is also a concern that the existing balance between customer service, competitive pricing, and intermediary sustainability could be disrupted.
The regulatory framework should therefore ensure that intermediaries receive reasonable remuneration while continuing to protect customers’ interests and encourage transparent, fair, and competitive pricing.
3. Specific Concerns Regarding Motor Insurance
Motor insurance is a highly competitive and price-sensitive segment in which customers frequently depend on intermediaries for guidance and premium comparisons. Customers need appropriate advice on coverage, add-ons, deductibles, claim procedures, and the availability of competitive premiums.
Any reform that reduces the ability or incentive of intermediaries to offer competitive discounts could negatively affect the customer experience. It is important to ensure that reforms do not unintentionally restrict genuine price competition or diminish the quality of advice provided to policyholders.
4. Impact on Employment and Insurance Intermediary Teams
An equally important concern is the potential impact on employment across the insurance intermediary ecosystem. If changes in commission structures significantly reduce business profitability, intermediaries may be forced to restructure their operations, reduce staff strength, or discontinue certain business activities.
Lakhs of employees and insurance executives working in sales, customer service, renewals, operations, and advisory functions could face uncertainty. These employees contribute directly to insurance distribution, customer education, and the growth of the insurance sector.
While regulatory reforms are important, their potential consequences for the livelihoods of intermediary employees and the sustainability of distribution networks must also be carefully evaluated.
5. Request for a Balanced and Consultative Approach
IRDAI has an important responsibility to protect policyholders and promote the orderly growth of the insurance industry. However, reforms should also consider the practical realities faced by intermediaries, their employees, and the customers who depend on their services.
I respectfully request IRDAI to:
Reassess the potential impact of the proposed reforms on insurance premiums, penetration, and policy renewals.
Ensure that intermediaries continue to receive fair and sustainable remuneration for their advisory and servicing responsibilities.
Preserve healthy competition and the ability to offer customers competitive insurance premiums, subject to regulatory requirements.
Conduct a detailed impact assessment of the proposed changes on employment across the insurance distribution ecosystem.
Consult insurance intermediaries, industry representatives, and employee groups before implementing changes that could substantially affect their businesses and livelihoods.
Conclusion
The objective of insurance reform should be to create a stronger, more transparent, affordable, and sustainable insurance ecosystem. Customer protection, competitive pricing, fair intermediary remuneration, and employment stability should be treated as interconnected priorities rather than competing interests.
I urge IRDAI to adopt a balanced approach that protects customers while also safeguarding the interests of intermediaries and the employees who form an essential part of India’s insurance distribution network.
A sustainable insurance industry requires not only sound regulation but also a viable distribution ecosystem capable of advising customers, retaining policyholders, expanding insurance coverage, and generating employment.
I can also help turn this into a stronger public appeal or formal representation to the IRDAI Chairperson, with specific arguments on how commission restrictions could affect motor insurance premiums, renewals, intermediary businesses, and jobs.