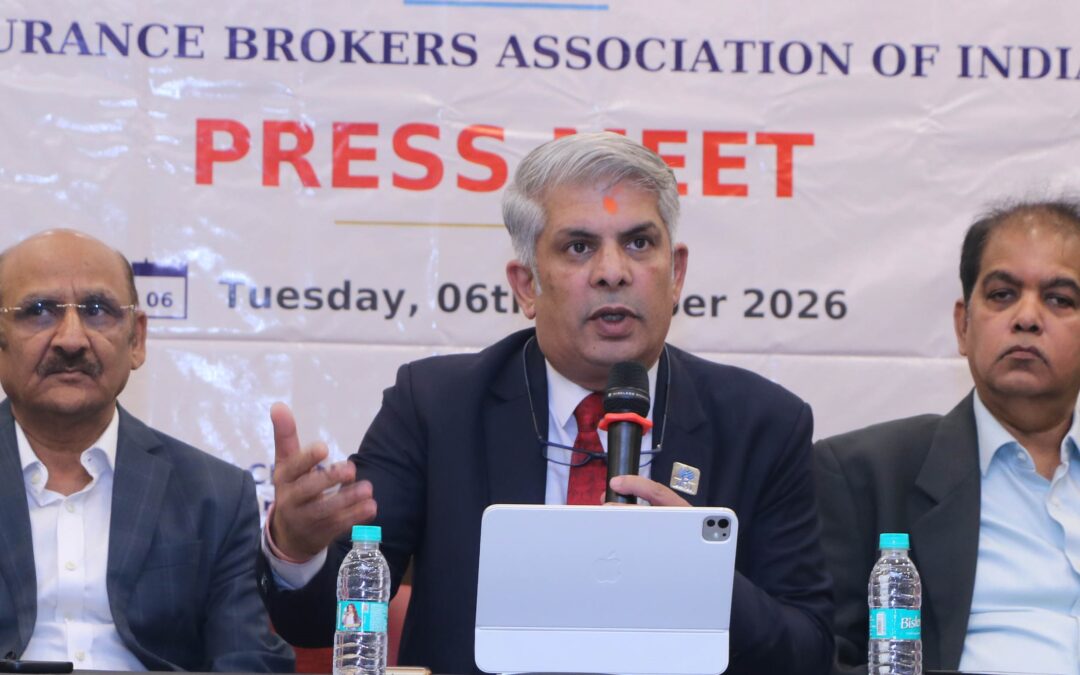
Brokers are seeking an extension of a deadline for consultation on the proposals to late December from October 25, an independent impact assessment, as well as the removal of caps on commission. The proposals could lower broker revenues by nearly 70%, IBAI President Narendra Bharindwal said.
Mumbai: India’s plan to overhaul how insurance products are sold and priced in Asia’s third-largest economy is facing pushback from brokers and automobile dealers, who say the rules could lead to job losses and disrupt distribution models.
The Insurance Regulatory and Development Authority of India has proposed capping commission paid across a swath of insurance products as well as curbs on overall expense limits for insurers to reduce mis-selling and lower policy costs.
The Insurance Brokers Association of India(IBAI), representing over 770 brokers, has written to Prime Minister Narendra Modi and the finance minister seeking intervention, cautioning that at least 1 million livelihoods are at risk over a five-year period.
The brokers’ body will meet the IRDAI chairman in the coming days to seek a review, a representative told reporters on Tuesday.
Brokers are seeking an extension of a deadline for consultation on the proposals to late December from October 25, an independent impact assessment, as well as the removal of caps on commission. The proposals could lower broker revenues by nearly 70%, IBAI President Narendra Bharindwal said.
“Within months of 100% FDI, a complete overhaul of distribution signals high regulatory uncertainty,” IBAI said in the letter dated October 2.
The Federation of Automobile Dealers Associations, representing over 15,000 dealers, is gathering feedback ahead of the October 25 deadline, FADA President Sai Giridhar told Reuters.
“It is not only selling vehicle insurance, it is the hand-holding that we do in the entire tenure of that policy,” Giridhar said. “I don’t think you’ll be able to sustain it with a 5% commission.”
India is the world’s 10th largest insurance market, with $124.4 billion in premiums in fiscal year 2025 across roughly 60 insurers, including global players such as Prudential and Sun Life Financial.
Earlier this year, New Delhi opened the sector to 100% foreign direct investment.
Still, insurance coverage in the world’s most populous country stands at 3.7% of gross domestic product, against an Allianz estimate of 7.2% for the global. Indian insurers largely depend on sales through financial brokers and bundled sales.
Shares of India’s listed insurance brokers PB Fintech and Turtlemint have fallen 45% and 49.4%, respectively, since IRDAI released the consultation paper on September 23.
Reuters