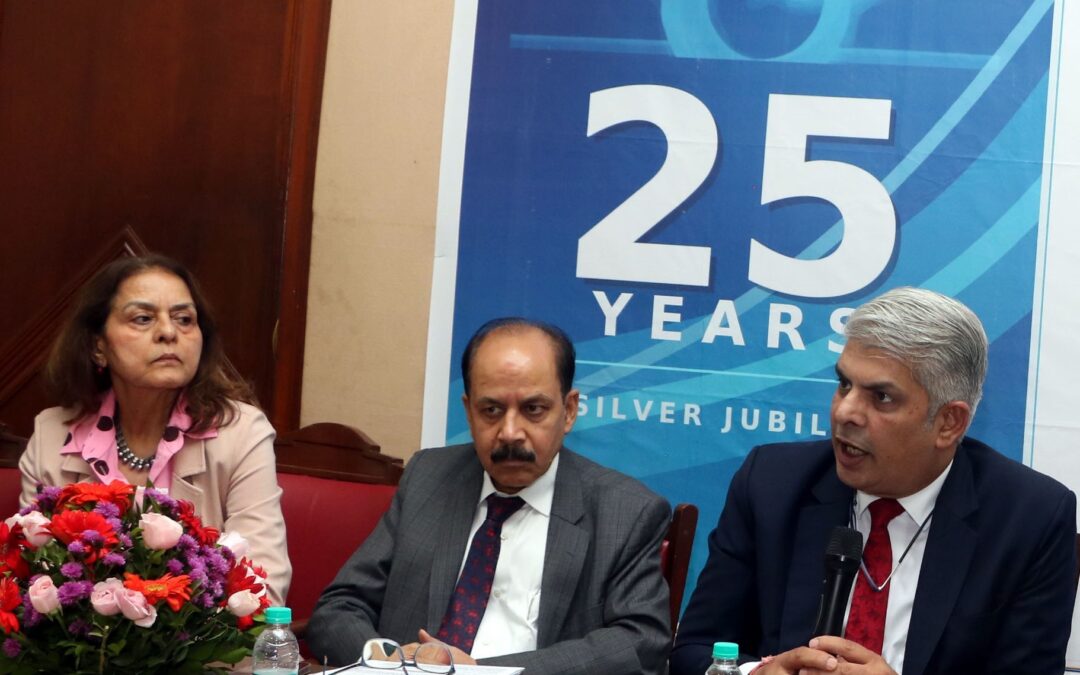
L-to-R- Functionaries of Insurance Brokers Association of India- Rashmi Iyer, director,Nirmal Bazaz, secretary, Narendra Bharindwal, president- at the AGM of the association in Mumbai on Saturday
“We are carefully reviewing the consultation paper to fully understand the scope, implications and intent of the proposals outlined by the regulator. While we have certain concerns regarding some of the proposed changes and their potential implications for the insurance ecosystem, we believe the consultation process provides an important opportunity for constructive stakeholder engagement,” said Narendra Bharindwal, President,Insurance Brokers Association of India
Mumbai:With a great deal of anxieties, the Insurance Brokers Association of India (IBAI), representing around 750 members, plans to engage with insurance regulator IRDAI over concerns arising from its latest consultation paper, “Recalibrating Economics of Insurance Distribution”, which proposes a comprehensive overhaul of insurance distribution economics, including expenses, commissions, market conduct, transparency and the use of digital infrastructure.
For insurance brokers,who almost channelise over Rs 50,000 crore of annual premium in Rs 3.36 trillion Indian general insurance market, the proposals could have significant implications for their operating economics, remuneration structures and the way distribution costs are managed across the insurance value chain.
The issue was among several matters discussed at IBAI’s annual general meeting, held on Saturday in Mumbai, where members deliberated extensively on regulatory and business challenges confronting the insurance broking community.
“We are carefully reviewing the consultation paper to fully understand the scope, implications and intent of the proposals outlined by the regulator. While we have certain concerns regarding some of the proposed changes and their potential implications for the insurance ecosystem, we believe the consultation process provides an important opportunity for constructive stakeholder engagement,” said Narendra Bharindwal, president, IBAI.
“We intend to engage with IRDAI in a positive, evidence-based and progressive manner, with the objective of contributing to a regulatory framework that protects policyholder interests, supports the sustainable growth of the insurance sector and advances the broader objective of Insurance for All,” Bharindwal added.
In its September 23 consultation paper, IRDAI has proposed tighter Expense of Management (EoM) limits, sharper controls on commissions and measures aimed at curbing mis-selling as part of a broader effort to recalibrate the economics of insurance distribution.
For general insurers, the regulator has proposed shifting the basis for EoM calculations from gross written premium (GWP) to domestic gross direct premium income (GDPI), with the ceiling progressively reduced from 30% of GWP to 20% of GDPI over five years.
For life insurers, the EoM ceiling would move to a company-level measure linked to GDPI, with the limit proposed to fall to 15% within two years and 12.5% within five years.
The consultation paper also proposes a more differentiated commission framework, taking into account the insurance segment, line of business, distribution channel, product complexity and the effort involved in sales and servicing. Additional rewards could be permitted for distribution in underserved markets, including rural areas, small towns with populations of up to 50,000 and smaller cities with populations of up to 10 lakh.
IRDAI has also proposed cost audits and safeguards against indirect payments to strengthen accountability for actual distribution costs.
The proposed framework seeks greater transparency from insurers and large distribution entities, including disclosure of commission policies and structures in a simple and accessible manner. Specified commercial insurance policies would also carry commission disclosures, providing customers with greater visibility into distribution costs embedded in premiums.
The proposals also seek to overhaul the insurance distribution architecture through simpler registration, lower entry and capital requirements, reduced regulatory fees and greater flexibility for distributors to undertake insurance alongside other financial and non-financial activities.
It seeks to replace the existing complex and fragmented architecture with three broad categories of distribution entities namely Insurance Distribution Entities (IDEs),Insurance Distribution Persons (IDPs) and Market Infrastructure Institutions (MIIs).
Entities operating under the same structure would have the same scope of business, obligations and regulatory framework. A clearer distinction between open and closed distribution architectures is proposed to promote competition while reducing regulatory arbitrage and operational constraints.
The reforms are aimed at making distribution more customer-facing, allowing policyholders to clearly understand who they are buying insurance through while expanding opportunities for Insurance Distribution Platforms (IDPs).
The proposed changes could also open the distribution market to entrepreneurs in smaller towns and markets, with the stated objective of expanding insurance reach, generating employment and improving income opportunities across the country, said the IRDAI.
The primary aim is to foster a customer-centric, competitive, efficient and transparent distribution ecosystem, while enabling better and sustainable outcomes for policyholders, insurers and distributors, said the IRDAI.
The last date for submission of comments and feedback on the consultation paper is 25 October .
Sir,
Please make bank stop selling insurance. The miss selling in bank at max level. Even in health and even life insurance also. In property for sure there will be no claim settlement.
Noted object.
How about customers demanding pass back and demanding unimaginable discounts . Also any light on how to curb certain customers who give multi mandates and bring in dog fight in pricing resulting in bare bone premiums ?