Efficiency matters, but not at the expense of long-term value creation for policyholders. Since distribution is a means rather than an end, the final framework should encourage persistency, meaningful post-sale engagement, and long-term customer outcomes,while removing incentives that favour unsuitable sales.
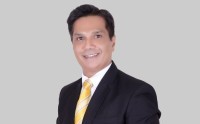
Rajat Srivastava, Chief Distribution Officer – Proprietary Channels, Aviva Life Insurance
India’s life insurance industry stands at a defining juncture. While life insurers collected ₹4.59 lakh crore in new business premiums, marking an impressive 15.7% 1 rise,insurance penetration remained stagnant at 2.7% of GDP. While premium growth indicates that the business is scaling, it does not signify whether enough families have adequate protection, understand what they have purchased, or can sustain it over time.
Against this backdrop, Insurance Regulatory and Development Authority of India (IRDAI)’s recent consultation paper titled, “Recalibrating Economics of Insurance Distribution”, brings up a pertinent question: what should our industry reward?
The answer lies in creating long-term value for customers rather than rewarding short-term transactions.
Simplification is key for successful distribution
Issuing a policy is merely the beginning of a long-term promise between an insurer and a policyholder. Distribution succeeds when that promise holds firm in moments that matter most to customers and their families.
The proposed simplification of the distribution architecture is a useful starting point. By clubbing intermediaries under three broad categories – Insurance Distribution Entities, Insurance Distribution Persons and Market Infrastructure Institutions – the regulator is seeking greater consistency, lower entry barriers and clearer accountability.
Moreover, the suggested distinction between open and closed distribution models could also encourage competition while preserving clarity for customers.
The prospect of allowing eligible distributors to offer other financial and non-financial services could also open new routes to customers. But simpler licences alone will not deliver inclusion. A wider network must be matched by better training, appropriate
advice and service that extends well beyond the point of sale. The more difficult debate concerns economics.
For instance, the paper proposes reducing life insurers’ expenses-of-management limits to 15% of premium within two years and 12.5% within five, alongside commission ceilings differentiated by product, channel and selling effort.
Efficiency matters, but not at the expense of long-term value creation for policyholders. Since distribution is a means rather than an end, the final framework should encourage persistency, meaningful post-sale engagement, and long-term customer outcomes,while removing incentives that favour unsuitable sales.
For example, an insurance advisor must spend considerable time understanding a household’s financial obligations to help customers navigate income changes, update protection needs, and maintain cover through difficult years.
Additionally, to avoid a system in which distribution becomes efficient only in locations that are already easy to serve, attention needs to be given to proposals for additional rewards in rural areas and smaller towns – where awareness is low and personal outreach is essential.
Overcoming the hurdle of misselling
With India recording a 14% year-on-year increase in complaints related to mis-selling and unfair business practices in FY2024–25 2 , the proposals on market conduct are equally consequential.
Stronger documentation of customer needs, greater visibility into commissions, accountability at the individual seller level, curbs on volume-linked incentives for bank and NBFC staff, safeguards against compulsory bundling with loans,and commission clawbacks in cases of misselling are not merely compliance measures.
These measures have the potential to better align distributor success with customer interests. Accountability for transparency, however, cannot rest with the regulator alone.
Insurers must also ensure that a suitable policy suggestion goes beyond an immediate conversion. While publishing commission policies is an important step, clarifying premiums, benefits, exclusions, risks and long-term commitments in plain language is the larger obligation.
Transparency will be meaningful only if customers can use the information provided and make a more confident choice.
At Aviva, we follow a staggered commission approach that encourages distributors to remain engaged with customers throughout the life of the policy, rather than concentrating incentives at the point of sale. This creates stronger alignment between customer interests, distributor behaviour, and long-term policy persistency, while encouraging continuous customer servicing.
Enabling digitalisation to ease complexity
The consultation paper recognises Market Infrastructure Institutions (MIIs) as digital, pull-based distribution platforms for insurance, adding another key dimension.
Envisaged as a customer-facing marketplace, Bima Sugam, and the proposed Public Insurance Registry could make things easier for customers in many ways. They will be able to discover products, access reliable information and reduce servicing friction.
However, the future of insurance lies in the partnership between algorithms and advisers, not in competition between the two.
Consequently, the strongest distribution model will offer both convenience and counsel, with digital platforms freeing people to focus on advice rather than paperwork.
For straightforward protection needs, customers may prefer a fully digital journey, while more complex financial decisions often benefit from personalised advice.
For insurance companies, this shift reinforces the importance of building quality across channels. Strengthening agency, alongside productive distribution partnerships, is already part of the industry’s publicly stated direction.
At Aviva, we continue to strengthen digital servicing capabilities and leverage data-led insights to identify customers who may require additional support before a policy is at risk of lapse or surrender.
Harnessing the bigger opportunity to achieve insurance for all
Ranked as the 10th largest insurance market globally by premium volume, India now has an opportunity to make insurance a trusted part of every household’s financial planning. As amends to compensation and operating models are bound to impact livelihoods, distribution capacity and the economics of reaching underserved markets,balanced restructuring of insurance distribution will be vital.
Committed to the vision of “Insurance for All by 2047”, success should not be assessed through expense ratios alone. Other indicators such as persistency, complaints, protection adequacy, customer understanding and outcomes over the policy lifecycle are equally important. Improving affordability, accessibility, and trust must remain the industry’s larger purpose.
Ultimately, these reforms will be successful when more Indian families can confidently choose, understand and benefit from life insurance protection.