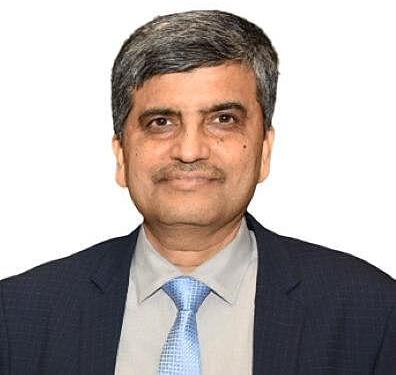
Ajay Seth,chairman , IRDAI
“The idea is to allow for an orderly transition from the present system to a better systemThere’s absolutely no intention that there should be a disruption for any market player or any individual.”Ajay Seth,chairman, IRDAI
Insurance Information Bureau is proposed to be transformed into a not-for-profit company that would host the.Public Insurance Registry,a digital platform aimed at improving insurance data sharing and making information more accessible to customers and financial institutions
Mumbai: India’s insurance regulator will ensure an “orderly transition” to proposed reforms governing insurance sales, with no intention of disrupting insurers or distributors, its chairman Ajay Seth said on Thursday.
The Insurance Regulatory and Development Authority of India (IRDAI) last month proposed capping commissions on a range of insurance products and tightening insurers’ expense limits to lower policy costs and curb mis-selling.
“The idea is to allow for an orderly transition from the present system to a better system,” Seth told reporters on the sidelines of SamvAAd 2026 India Open Finance Summit, in Mumbai.
“There’s absolutely no intention that there should be a disruption for any market player or any individual.”
Seth, who met insurers and distributors this week, said their requests so far have been relaxations for smaller players and low-value policies, along with a transition path.
However, no one has objected to the problems the regulator identified or the broad direction of the reforms, he said.
The rules could take effect from January or April 1 next year, depending on industry feedback, Seth said.
A draft regulation will follow the consultation, giving stakeholders another chance to comment.
Brokers have sought to push the October 25 consultation deadline to late December, Reuters reported earlier this month. Seth did not commit to an extension and urged stakeholders to send their comments on time.
Meanwhile, IRDAI is looking at January 2028 for the beta launch of its proposed Public Insurance Registry (PIR), a digital platform aimed at improving insurance data sharing and making information more accessible to customers and financial institutions, Seth said. on Thursday.
Speaking at the SamvAAd 2026 India Open Finance Summit, Seth said the Insurance Information Bureau(IIB) is proposed to be transformed into a not-for-profit company that would host the registry.
“This will be the Insurance Information Bureau getting transformed into a not-for-profit company and being the host of PIR. We are talking about a beta version in January ’28,” Seth said during a discussion on digital financial infrastructure.
The announcement comes as the regulator works towards creating a common digital framework for the insurance sector, where information is currently maintained in different formats across insurers, making data sharing and comparison difficult.
Seth also announced that the deadline for stakeholders to submit feedback on the Public Insurance Registry consultation paper had been extended from September 30 to October 17, 2026.
He urged industry participants to provide suggestions on how the proposed system could be improved.
Explaining the need for the registry, Seth said the insurance industry currently lacks common standards for collecting, storing and exchanging data.
“At the moment, there are about 60 insurers. But if you ask whether the data is standardised with them, the way they store the data, the way they collect the data? No,” he said.
The proposed registry would help establish common standards and protocols, allowing information to move more easily between insurers and other financial institutions.
Seth said IRDAI had identified eight potential use cases for the registry, of which six would require participation from the Account Aggregator (AA) ecosystem.
These include premium financing, assessing insurance requirements, using insurance histories for lending decisions and supporting surety bonds as alternatives to bank guarantees.
He clarified that the Public Insurance Registry and Bima Sugam, the proposed digital insurance marketplace, would serve different purposes.
While Bima Sugam is designed as a customer-facing platform for purchasing insurance directly, the Public Insurance Registry would primarily support businesses and financial institutions by standardising and facilitating the exchange of insurance information.
They are not a replacement; they are complementing each other,” Seth said, referring to the proposed platforms and existing digital public infrastructure.
The IRDAI Chairman also acknowledged that standardising historical insurance records would take time, as insurers would need to update existing customer information, including during policy renewals and claims.
He said the regulator would focus on setting standards for new information while gradually improving older records.
The proposed registry is expected to support greater transparency in the insurance market by making standardised information about products, insurers and distributors available for comparison.
However, Seth indicated that building the necessary data standards and infrastructure would be a gradual process, with January 2028 currently being discussed as the timeline for a beta version rather than the full launch.
India is the world’s 10th-largest insurance market, with $124.4 billion in premiums in fiscal 2025 across roughly 60 insurers, including Prudential (PRU.L), and Sun Life Financial.
The proposed rules are part of the IRDAI’s push to reform the sector after New Delhi this year opened it to 100% foreign ownership, and target costs it says have ballooned since commission limits were scrapped in 2023.